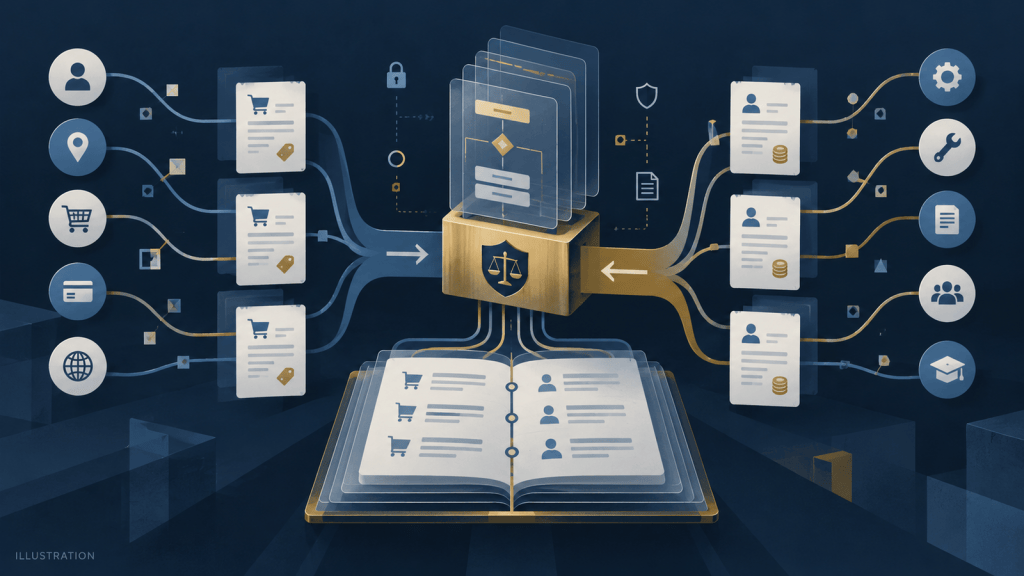
The Federal Trade Commission has opened a wide-ranging inquiry into how major airlines, retailers, ride-sharing platforms and delivery companies use personal data to set prices and worker compensation. For finance leaders, the important issue is broader than regulatory exposure: a pricing model becomes a financial-control system when it determines revenue, margin, customer treatment and labor cost at scale.
The judgment
- Implication: Personalized pricing and compensation should be governed as end-to-end finance processes, not left solely to data science, marketing or operations. The control environment must connect model inputs to price approval, customer disclosure, revenue reporting and worker payments.
- What would change the conclusion: Evidence that the models use limited, clearly disclosed inputs; apply consistent policy constraints; retain auditable decision records; and undergo independent testing would reduce the case for treating them as unusually high-risk financial systems.
- Management action: Build one control map covering the data used, the model or rules applied, permitted overrides, price and pay outputs, disclosures, accounting treatment, monitoring and escalation. Finance should be able to explain why two otherwise comparable transactions produced different economics.
On October 28, the FTC issued compulsory information orders to Delta, United, JetBlue, Lyft, Uber, DoorDash, Instacart, Target and Walmart. The agency said it wants to study whether personal data, loyalty-program participation and algorithmic analysis are used to vary prices from one person to another or to alter compensation offers to gig workers.
The orders were issued under Section 6(b) of the FTC Act. Recipients have 45 days after receiving them to respond. The FTC emphasized that the study does not itself have a specific law-enforcement purpose. The inquiry therefore is not a finding that any named company violated the law, and it should not be described as one.
The reported facts in this article come from the FTC materials linked below. The control framework and management conclusions are Numbers & Judgment analysis.
Pricing becomes a control process when the inputs are personal
Companies have always varied prices. Airlines use inventory, route, timing and demand. Retailers use promotions, geography, inventory levels and loyalty programs. Delivery and ride-sharing platforms adjust offers as supply and demand change. Variation by itself is not evidence of deception.
The control problem changes when a company uses information about a particular consumer or worker to estimate the highest acceptable price or lowest acceptable compensation. The economic output may look like an ordinary transaction, but the decision path can depend on browsing behavior, device activity, prior acceptance history, loyalty status or other signals that the affected person cannot see.
That opacity creates several finance questions at once:
- Is the price difference consistent with an approved commercial policy?
- Does the company disclose the use of personal data accurately?
- Can management reproduce the decision after the transaction?
- Are overrides authorized and monitored?
- Does the revenue system preserve the approved price, discounts and consideration correctly?
- Do compensation outputs flow completely and accurately into payroll or contractor-payment systems?
- Can finance distinguish model-driven margin improvement from changes in volume, mix or service level?
A model that cannot answer those questions may still optimize a short-term metric. It is not yet a controlled financial process.
The ledger starts upstream
Finance controls often concentrate on the end of the process: whether the invoice was posted, revenue was recognized and the payment was recorded. Personalized pricing pushes the most consequential judgment further upstream.
The selected data, model objective and permitted constraints may determine the transaction before an accounting entry exists. If a system is rewarded only for conversion, margin or driver acceptance, it may learn a financially effective pattern that is inconsistent with management’s stated policy or consumer disclosures. A technically accurate journal entry does not cure a poorly governed price.
This is closely related to the contract-governance issue examined in Endava Probe Puts Contract Controls Upstream of the Ledger. The system of record is only as reliable as the commercial decisions feeding it.
Separate model performance from policy compliance
A personalized-pricing model can be statistically strong and still produce unacceptable outcomes. Accuracy answers whether the model predicts behavior. It does not answer whether the inputs are appropriate, disclosures are complete, outcomes are consistent with policy or the company can defend the resulting customer and worker treatment.
Management reporting should therefore separate at least four dimensions:
- Commercial performance: conversion, revenue, unit economics, retention and incremental margin.
- Outcome dispersion: how prices or pay differ among comparable transactions and which variables explain the difference.
- Control performance: override rates, exception volume, missing decision records, unresolved data-lineage issues and testing results.
- Conduct signals: complaints, disclosure mismatches, adverse trends for identifiable groups and regulator or legal inquiries.
The same principle appeared in An Algorithm Does Not Neutralize a Sales Conflict: automation can scale a decision, but it does not remove the incentive or governance problem surrounding that decision.
Worker compensation belongs in the same map
The FTC inquiry is notable because it examines both customer prices and worker compensation. Those are usually owned by different teams and may sit in different systems, yet together they determine the platform’s transaction-level spread.
That makes fragmented governance especially risky. Revenue operations may optimize customer price while workforce systems optimize driver or courier pay, with finance seeing only the resulting net margin. A complete control view should connect both sides of the transaction and show whether one model’s improvement depends on a cost shift produced by another.
Finance does not need to approve every real-time offer. It does need sufficient evidence to reconcile aggregate results back to approved rules and to investigate unexpected changes in price, pay, volume or margin.
A practical governance package
Boards and audit committees do not need source code. They need a concise package that makes accountability visible. A useful package would include:
- the approved business objective and prohibited uses;
- an inventory of personal and transactional data inputs;
- ownership across product, data science, legal, privacy, finance and internal audit;
- model-change approval and version history;
- tests for reproducibility, outcome dispersion and disclosure consistency;
- override authority and monitoring;
- complaint and exception trends;
- financial reporting and compensation-system interfaces; and
- a defined response when performance improves while a control indicator deteriorates.
The last item matters. A model can create measurable financial value while simultaneously increasing conduct or control risk. Management should not blend those results into one favorable return calculation.
Forecast the response, not only the outcome
The FTC study may lead to additional guidance, enforcement priorities or no immediate rule change. The current record does not justify predicting which outcome will occur. Finance teams can still prepare scenarios tied to observable developments: broader information requests, required disclosure changes, limits on particular data inputs, retrospective testing or no material change.
Numbers & Judgment’s free Forecast Scenario Planner can help separate those cases and connect each to management actions. Potential financial drivers include conversion, average realized price, promotion cost, worker compensation, implementation expense, complaint handling and legal or remediation cost. The purpose is not to estimate a regulatory outcome precisely; it is to avoid waiting for certainty before identifying the operational response.
The finance question
Personalized pricing is often framed as a privacy, competition or technology issue. It is also a core finance issue because the model determines the economics of individual transactions and can influence reported revenue, margin and labor cost at enormous scale.
The immediate FTC action is an inquiry, not a judgment. The management lesson is available now: when personal data changes what a customer pays or a worker earns, the organization should be able to reconstruct the decision, demonstrate that it followed approved policy and show how the resulting economics reached the financial statements.
Sources
- Federal Trade Commission, “FTC Launches Personalized Pricing and Compensation Inquiry,” October 28, 2026.
- Federal Trade Commission, proposed enforcement-policy statement regarding personalized pricing, August 2026.
By Robert Young | Numbers & Judgment. Published October 28, 2026.


Leave a Reply