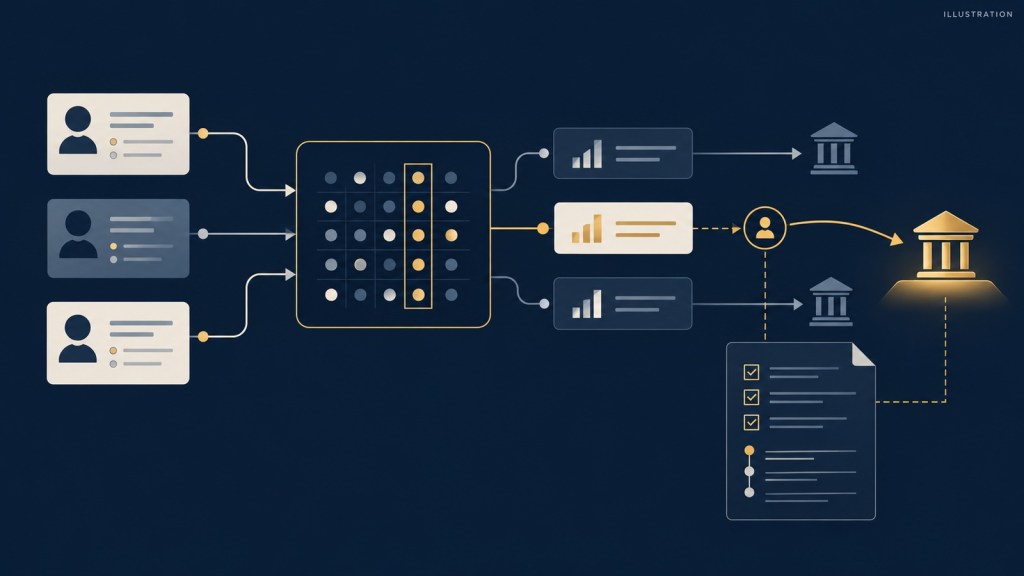
The SEC’s September 28 case against Zoe Financial is a useful warning for any finance organization putting an algorithm between a customer and a commercial recommendation. A neutral matching model does not neutralize the economics around it. If people can override the model—and if the firm earns more from some outcomes than others—the control problem moves from the algorithm to the full recommendation workflow.
The SEC said Zoe operated a referral service that used an algorithm to match prospective clients with investment advisers. Salespeople then followed up with users who did not schedule a meeting and often suggested additional advisers beyond the algorithm’s matches. After Zoe launched its own wealth platform, the SEC found that the firm had a financial incentive for advisers to use that platform and did not adequately disclose the resulting conflict until December 2024.
The judgment
- Implication: A recommendation process should be governed end to end. A model can be unbiased while the surrounding sales process remains conflicted.
- What would change the conclusion: The risk would be lower if human overrides were rare, independently reviewed, economically neutral and disclosed before the recommendation. The SEC’s findings make clear that technology alone is not enough evidence of neutrality.
- Management action: Log every human override, map the compensation attached to each destination, require exception review when the override improves the firm’s economics, and trigger disclosure review whenever a new product, affiliate or revenue stream changes the incentive structure.
What the SEC found
In its September 28 press release, the SEC said Zoe Financial matched users with third-party investment advisers through an algorithm and then used salespeople to follow up with users who had not scheduled a meeting. Those salespeople often recommended advisers that were not among the algorithm’s initial matches.
The SEC said Zoe launched Zoe Wealth in January 2023, offering sub-advisory services, account onboarding and other back-office support to advisers in its network. The order found that Zoe had a financial incentive for advisers to use that platform. According to the SEC, the algorithm itself did not consider whether an adviser used Zoe Wealth, but salespeople often became involved and sometimes recommended advisers outside the algorithm’s results. The SEC said Zoe did not adequately disclose the resulting conflict in its Form ADV Brochure until December 2024.
The SEC also said Zoe disclosed that some advisory firms held indirect minority interests in the company but did not accurately describe how it mitigated that conflict. Without admitting or denying the findings, Zoe agreed to a cease-and-desist order, a censure and a $450,000 civil penalty. The SEC’s order also credited remedial measures, including revisions to Zoe’s compliance manual and the hiring of an in-house chief compliance officer.
Those are reported regulatory findings. The control conclusions below are Numbers & Judgment analysis.
The control boundary is wider than the model
It is tempting to treat an algorithm as the decision engine and everything around it as implementation. That distinction breaks down when a human can redirect the outcome.
Suppose a matching model selects three advisers without using referral fees, affiliate status or platform participation. That is useful evidence about the model. But if a salesperson can then recommend a fourth adviser—and the firm earns more if the client chooses that adviser—the economic conflict has moved downstream. The model may be neutral while the process is not.
This is the same broader governance issue raised in The Australian AI-Agent Breach Makes Segregation of Duties a Machine Problem: the meaningful control boundary is the full sequence of actions, permissions and overrides. A clean first step does not cure an uncontrolled later step.
Four controls that matter more than “the algorithm is neutral”
1. Override logs
Every recommendation added, removed or reordered by a person should be traceable to a named user, timestamp and reason. The log should preserve both the original algorithmic output and the final recommendation presented to the customer.
This is not only a compliance artifact. It is management information. If overrides cluster around one platform, product, affiliate or revenue stream, the pattern may reveal a commercial incentive that the formal model never sees.
2. Incentive mapping
Finance should map the economics attached to each possible recommendation: referral fees, platform fees, implementation revenue, ownership interests, revenue-sharing arrangements and other direct or indirect benefits. The purpose is not to prove misconduct. It is to make conflicts visible before someone has to infer them from outcomes.
The SEC’s June Risk Alert on economic conflicts of interest makes the same point from the regulatory side: advisers need policies, procedures and disclosures that address the economic incentives that can influence recommendations.
3. Exception review
An override should receive more scrutiny when it improves the firm’s economics. That does not mean the recommendation is wrong. It means the evidence supporting it should be stronger and independently visible.
A practical rule is to flag any human change that moves a client toward an option with higher revenue to the firm, an ownership relationship, an affiliated service or a different fee arrangement. Compliance can then review the reason and the disclosure rather than trying to reconstruct the decision months later.
4. Disclosure triggers
Disclosure should not be a once-a-year document exercise. New products, affiliates, service lines, ownership changes and compensation models can change the conflict structure even if the recommendation algorithm itself is untouched.
The SEC’s case is a reminder that launching a new technology or new feature can create a new disclosure problem. Management should therefore connect product launches and compensation changes to a formal conflict review before the workflow reaches customers.
Why this belongs on the CFO agenda
Conflicts of interest are usually framed as a legal or compliance matter. The economics are finance territory.
The CFO or finance leader can help answer four questions that are easy to miss in a purely technical review:
- Which recommendation paths generate different economics for the firm?
- Which employee compensation plans could favor one path over another?
- Which overrides are material enough to require independent review?
- How much revenue depends on arrangements that require especially clear disclosure?
This is also where AI and automation governance becomes a capital-allocation question. As discussed in AI ROI Is a Finance Problem, Not a Technology Problem, the return case for automation should include the cost of controls, review, exception handling and evidence retention—not treat those as overhead discovered after deployment.
The free AI & Automation ROI Calculator can help make that cost explicit when a workflow includes automated matching, recommendations or sales support.
A useful test for any recommendation system
Management can test the workflow with five questions:
- What does the algorithm recommend before any human intervention?
- Who can override, add or reorder those recommendations?
- Does the firm earn more from any of the available outcomes?
- Is that economic difference visible to compliance when an override occurs?
- Would the customer understand the conflict from the disclosure in place at the time of the recommendation?
If the answers are stored only in different systems—product, CRM, compensation, compliance and finance—the organization does not yet have an end-to-end control. The point is not to eliminate human judgment. It is to ensure that human judgment does not become an invisible path around a supposedly neutral model.
Bottom line
An algorithm can remove one source of bias from a recommendation process. It cannot remove the incentives of the organization operating around it.
The durable control is therefore not “trust the model.” It is: preserve the model’s output, log the override, expose the economics, review the exception and update the disclosure when the business changes.
Sources
- U.S. Securities and Exchange Commission, “SEC Charges Registered Investment Adviser Zoe Financial for Failure to Disclose Conflict of Interest,” September 28, 2026.
- SEC Division of Examinations, “Examinations Observations of Investment Adviser Obligations Related to Economic Conflicts of Interest,” June 9, 2026.
- Zoe Financial, Solicitation Disclosures, accessed September 28, 2026.
Reported enforcement facts above are attributed to the SEC. Process, governance and management recommendations are Numbers & Judgment analysis.


Leave a comment