October 14, 2026 · News Analysis · Robert Young
Bank of America’s $1.21 billion regulatory resolution is not only a large penalty. It is a case study in what happens when a control backlog grows faster than management’s ability to detect, investigate and close it.
The U.S. Treasury said on October 13 that Bank of America failed to report more than $5 billion in suspicious transactions on time, including more than $1 billion tied to national-security and other priority illicit-finance risks. Treasury also said suspicious activity accumulated without investigation for extended periods and that the bank relied too heavily on law-enforcement inquiries, other financial institutions and similar interventions instead of its own proactive controls.
The bank booked a $1.2 billion non-tax-deductible charge in its third-quarter results. That is the accounting event. The finance question is whether management can now demonstrate that the operating backlog, data gaps and escalation failures are actually shrinking.
The judgment
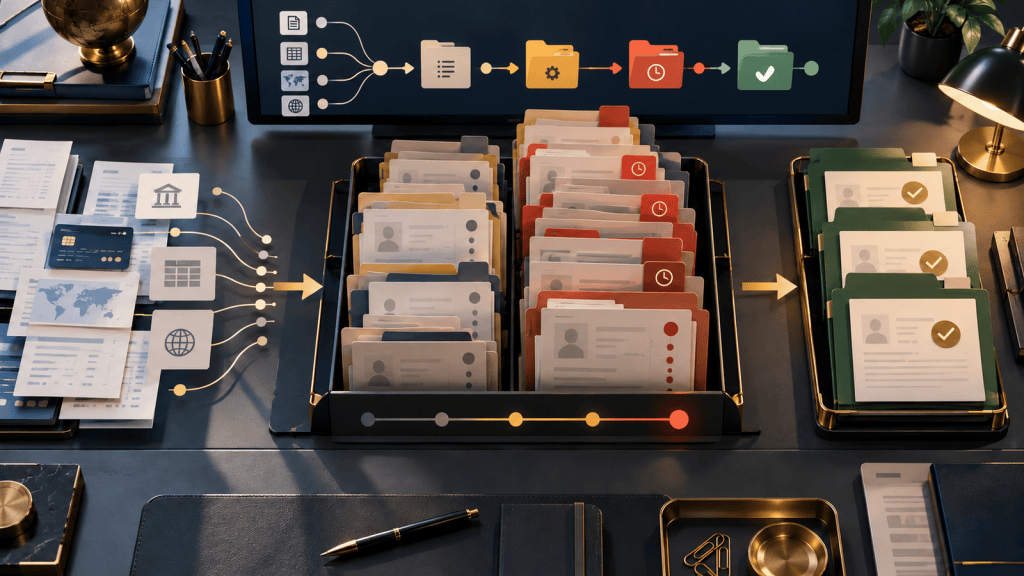
- Implication: A control program should be managed as a flow system. Alert volume, investigation capacity, case age and data coverage can deteriorate long before a penalty reaches the income statement.
- What would change the conclusion: Verified evidence of sustained backlog reduction, timely escalation, broader monitoring coverage and independent validation would show that the problem is moving from containment to durable remediation. Spending and staffing increases alone would not establish that result.
- Management action: Put control-backlog aging, unresolved high-risk exceptions, false-negative testing and critical data-lineage defects on the finance and board dashboard, with named owners and dated closure commitments.
The reported failures describe a broken flow
Treasury’s account describes several connected failures. Bank of America admitted that it willfully violated the Bank Secrecy Act, failed to maintain a compliant anti-money-laundering program, did not perform required due diligence for certain foreign correspondent accounts, and failed to file suspicious activity reports as required.
The most transferable finding is operational. Treasury said suspicious activity accumulated uninvestigated for extended periods. The OCC said the transaction-monitoring system failed to properly monitor trillions of dollars of transactions, producing large numbers of late reports involving billions of dollars. It also said management knew for years that potentially suspicious activity was not reaching investigators for review.
That is a queue-management failure as much as a policy failure. A system can generate alerts and still be ineffective if alerts are not risk-ranked correctly, if cases wait too long for investigation, or if the underlying data does not identify the customer, counterparty and transaction pattern accurately enough to support a decision.
The penalty is recognized before the remediation is finished
Bank of America’s third-quarter results included the $1.2 billion charge, reducing earnings by roughly 17 cents per share, according to Reuters. The bank reported $6.9 billion of net income and $30.0 billion of revenue. Net interest income increased 8%, while sales and trading revenue fell 5% and fixed-income, currency and commodities revenue fell 17%.
Those numbers illustrate why the charge should not be treated as the full cost of the event. The settlement creates a measurable accounting expense now. The consent order also requires a third-party lookback, independent review and continuing work on suspicious-activity monitoring, customer due diligence, correspondent-account due diligence and the data-governance framework supporting the program.
Future cost can therefore appear through several channels: remediation staffing, external advisers, technology changes, duplicated review, delayed product work, constrained management attention and potentially lower capital flexibility. Reuters reported that analysts questioned the effect on expenses and the bank’s share-repurchase pace, although regulators did not impose an asset cap.
The defensible forecast is not to assume every possible cost will materialize. It is to separate the booked charge from the unresolved operating obligation and attach ranges, milestones and decision triggers to the latter.
A remediation dashboard needs throughput, not activity
Management teams often report remediation through inputs: dollars spent, people hired, consultants engaged, models installed and policies rewritten. Those measures show effort. They do not show whether risk is leaving the system faster than it enters.
A finance-led dashboard should make the control flow visible:
- Intake: alerts and exceptions created by risk tier, product, geography and monitoring rule.
- Inventory: open cases by age, including the oldest unresolved high-risk item and the share beyond policy limits.
- Throughput: investigations closed, escalations completed and required reports filed on time, compared with new inflow.
- Coverage: material transaction types, customer attributes and counterparties that are absent, delayed or unreliable in the monitoring data.
- Quality: false negatives found through testing, reopened cases, repeat audit findings and exceptions that recur after claimed closure.
If new high-risk work continues to enter faster than validated work closes, the organization is still accumulating exposure even when head count and spending are rising.
Data governance belongs in the financial forecast
Treasury’s required independent review explicitly includes the data-governance framework used by the anti-money-laundering program. That is an important distinction. A control model cannot compensate for missing, late or poorly linked source data.
For finance leaders, critical data defects should be forecast like other operating constraints. A remediation plan should identify the affected systems, interim manual controls, validation work, expected completion dates and the financial capacity reserved if timelines slip. The same discipline applies outside banking when revenue systems, contract data, donor restrictions or payroll inputs feed a control process.
This extends the lesson in Endava Probe Puts Contract Controls Upstream of the Ledger: control quality depends on the information created before an accounting entry or compliance review is performed.
The board should distinguish cost, progress and closure
Bank of America said it has invested billions of dollars in technology and assigned thousands of employees to financial-crime compliance. Those commitments are material, but regulators still required further independent work. The gap between resources deployed and outcomes verified is the governance issue.
The recent Numbers & Judgment analysis of American Express’s $350 million penalty focused on aligning compliance capacity with business scale. Bank of America adds a sharper question: is capacity converting aged risk into timely, validated closure?
A board should therefore receive three separate views:
- Cost: current-period expense, capitalized technology and forecast external support.
- Progress: backlog, throughput, coverage and validation trends against milestones.
- Closure: independently verified findings resolved without recurrence, including remaining regulatory dependencies.
The free Board Finance Dashboard can provide the reporting structure for decisions, warning flags and ownership. A regulated institution would need to add program-specific measures with compliance and legal review.
The earnings comparison still matters
Bank of America’s operating results do not overturn the broader conclusion from Big Banks Report Growth Without a Broad Credit Break. Higher loan and deposit balances helped net interest income, and the penalty is not evidence of a systemwide credit downturn.
It does show that reported earnings strength and control health can move independently. A business can grow, generate cash and still carry an expanding operational obligation that is not visible in conventional margin analysis until enforcement, remediation or disruption makes it visible.
The finance discipline is to keep those questions separate: assess the earnings quarter on its own facts, recognize the booked charge, and track the unresolved control backlog until independent evidence supports closure.
Sources and method
- U.S. Treasury, “U.S. Treasury Announces Record Enforcement Actions Against Bank of America,” October 13, 2026.
- Reuters, “Bank of America fined $1.2 billion by US government for failing to police suspicious activity,” October 13, 2026.
- Bank of America, third-quarter 2026 results and presentation materials, October 14, 2026.
- Reuters, Bank of America third-quarter results, October 14, 2026.
Regulatory findings, company results and attributed statements are reported facts from the cited sources. The conclusions about backlog management, forecasting and board oversight are Numbers & Judgment analysis, not legal advice or a prediction of further enforcement.


Leave a Reply