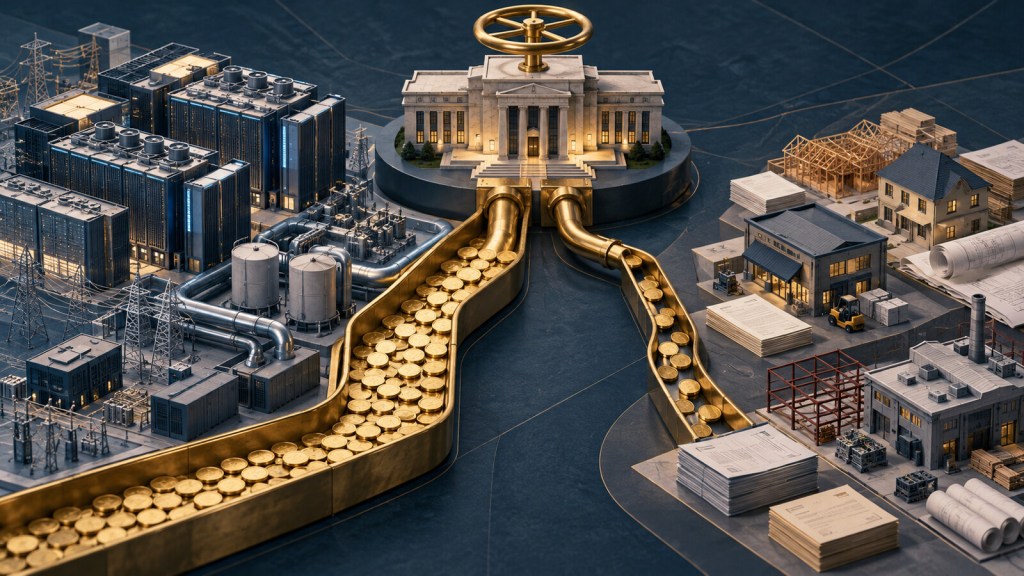
The Federal Reserve’s next inflation problem may be less about whether higher rates reduce demand than about whose demand they reduce. Artificial-intelligence infrastructure spending is adding to near-term price pressure, while many of the largest buyers can fund projects from cash flow and are comparatively insensitive to borrowing costs. Rate increases can therefore land hardest on households, small businesses and non-AI investment without directly slowing the source of the new demand.
That is not an argument for ignoring inflation or predicting the Federal Reserve’s October 27–28 decision. It is a planning signal: the same policy move can leave one capital program largely intact while making another organization’s customers, suppliers and refinancing plan materially weaker.
The judgment
- Implication: AI-linked demand can keep rates higher even when non-AI activity is already slowing, so finance teams should not treat the policy rate as a uniform brake across customers, suppliers or projects.
- What would change the conclusion: A sustained moderation in data-center investment, easing equipment and power bottlenecks, or clear evidence that AI productivity is reducing costs faster than the buildout is raising demand would make the rate burden less uneven. One softer data release would not settle the question.
- Management action: Separate AI-sensitive revenue and costs from credit-sensitive revenue and costs in the forecast. Reprice financing, test customer demand and supplier resilience, and set explicit triggers for delaying long-duration capital commitments.
AI is changing the transmission problem
Reuters reported on October 19 that Federal Reserve officials increasingly recognize the AI buildout as a source of demand and price pressure. The article’s central concern is distribution: hyperscalers and other large technology companies may keep spending through higher rates, while credit-dependent households and smaller businesses absorb more of the adjustment. Cleveland Fed President Beth Hammack described higher rates as cooling activity outside the boom “at the margins,” according to the report.
The official record supports the broader premise. The Federal Reserve’s July meeting minutes attributed part of the rise in inflation to demand from the AI buildout. Its July Monetary Policy Report said business fixed investment grew at an 11% annual rate in the first quarter, with most of the strength apparently connected to AI infrastructure, while non-AI investment was comparatively weak.
Governor Lisa Cook said on September 28 that AI appeared to be adding inflation pressure in the short term even though productivity could modestly ease it later. Governor Michael Barr said a day later that AI-related investment demand was having a measurable effect on prices. The September meeting minutes, released October 7, nevertheless projected those effects would wane over time. The evidence therefore supports a present tension, not a permanent inflation claim.
The policy tool is broad; the demand shock is concentrated
A central bank changes a short-term interest rate. The effect then moves through mortgages, credit cards, bank loans, bond yields, asset prices, exchange rates and expectations. That mechanism works, but not evenly.
A cash-rich company with a strategic need for compute, signed customer demand and scarce power access may accept a higher hurdle rate or finance less of the project with debt. A small manufacturer renewing a bank facility, a developer facing weaker housing demand or a household carrying revolving balances has fewer ways to avoid the price of credit.
This is the distinction between policy effectiveness and policy incidence. Inflation can still decline if higher rates suppress enough demand somewhere in the economy. The finance question is where the suppression appears first—and whether an organization’s plan is exposed to that part of the economy.
Four forecast lines need separate treatment
1. Customer demand
Do not apply one macro growth adjustment across the revenue forecast. Split customers by financing sensitivity, required payback period and exposure to housing, construction, discretionary consumption or leveraged investment. A customer whose expansion depends on a new loan may react to rates very differently from a hyperscaler reserving data-center capacity.
2. Working capital and counterparty risk
The first sign of tighter credit may be slower collections, smaller orders, requests for deposits or shorter supplier terms—not an immediate change in headline GDP. Finance should pair the sales outlook with customer aging, credit-limit usage, supplier concentration and the amount of liquidity trapped in inventory or receivables.
3. Financing cost and access
The policy rate is only one input. Refinancing depends on benchmark yields, credit spreads, bank appetite, covenants and the timing of maturities. As discussed in Bond Selloff Tightens Financing Before the ECB Moves, market transmission can change the effective cost of capital before a central bank changes its official rate.
4. Capital allocation
Projects should be tested against the financing environment they may actually face, not the rate used when the annual plan was approved. The earlier analysis AI Capital Spending Is Raising the Hurdle Rate for Its Own Investments focused on AI projects feeding back into their own funding cost. The new issue is wider: the same boom can raise the hurdle rate for projects that have no AI exposure at all.
Build a two-channel scenario
A useful forecast should not reduce the situation to “rates up” or “rates down.” It should keep two channels visible.
- AI-demand channel: data-center construction, chips, power equipment, cooling, network infrastructure, specialized labor and the suppliers serving them.
- Credit-sensitive channel: housing, consumer durables, small-business investment, conventional construction, leveraged transactions and any customer whose purchase depends on external financing.
For each channel, finance should identify volume, price, margin, working-capital and capital-spending assumptions. The free Forecast Scenario Planner can keep base, downside and relief cases tied to management actions rather than compressing them into one blended macro assumption.
The downside case should not assume every business weakens at the same speed. It could combine persistent AI-related input demand with weaker credit-sensitive revenue, higher financing costs and slower collections. The relief case should require evidence that the buildout’s price pressure is easing or that productivity gains are arriving—not merely a favorable market session.
What the board should see
The board does not need a forecast of the next Fed vote. It needs an exposure map that answers:
- Which revenue lines benefit from AI investment, and which depend on affordable credit?
- Which customers and suppliers have the least liquidity buffer?
- Which maturities, leases or capital commitments reprice first?
- Which projects remain attractive if the cost of capital stays higher for longer?
- What evidence would justify delaying, resizing or restarting a commitment?
The larger judgment is that monetary tightening is not a neutral tax on all demand. When the strongest investment cycle is concentrated among firms with abundant internal funding, the adjustment can migrate elsewhere. Finance teams cannot control that distribution, but they can stop hiding it inside one interest-rate assumption.
Sources
- Reuters, “Fed sees AI boom adding to inflation headache, but others may pay for the medicine,” October 19, 2026.
- Federal Reserve, minutes of the July 28–29, 2026 FOMC meeting, released August 19, 2026.
- Federal Reserve, Monetary Policy Report, July 2026.
- Federal Reserve Governor Lisa Cook, “An Update on AI and the Economy,” September 28, 2026.
- Federal Reserve Governor Michael Barr, “Economic Conditions and Monetary Policy,” September 29, 2026.
- Federal Reserve, minutes of the September 15–16, 2026 FOMC meeting, released October 7, 2026.
Reported facts and quotations are attributed to the sources above. Forecast design, management actions and capital-allocation conclusions are Numbers & Judgment analysis.


Leave a Reply