FICC’s $6 Billion Fund Plan Tests Who Pays for Treasury Risk
The SEC has opened proceedings on FICC’s proposed Treasury-market guaranty fund. The design could protect initial margin and release bank capital, but it would also create a separate cash obligation whose burden may fall differently across dealers.
The Securities and Exchange Commission said on November 5 that it would determine whether to approve or disapprove the Fixed Income Clearing Corporation’s proposal for a new guaranty fund at its Government Securities Division. The proceeding does not signal a conclusion. It does make the proposal’s tradeoffs a live Treasury-market decision rather than a technical footnote.
The reported facts below come from the SEC order, FICC’s filing and response, and public comment letters. The roughly $6 billion figure is FICC’s historical impact-study estimate for 2025, not a forecast or an approved fund size. The conclusions about liquidity, capital and management controls are Numbers & Judgment analysis.
The judgment
- Implication: Separating initial margin from mutualized default resources can improve the legal and capital treatment of margin, but the benefit should not be treated as universal. A new cash-only fund can release one constraint while tightening another.
- What would change the conclusion: The case for the proposal would strengthen if final implementation data show that capital relief, margin efficiencies and competitive access offset the new cash requirement across both bank-affiliated and independent dealers. It would weaken if the burden concentrates intermediation in firms already benefiting most from the capital treatment.
- Management action: Treasury-clearing members should model the proposal as three separate exposures—cash funding, regulatory capital and mutualized loss—not as one net number, and should test same-day liquidity for an intramonth resizing before relying on expected capital relief.
What FICC wants to change
FICC’s Government Securities Division is a central counterparty for U.S. government-securities transactions, including repo and reverse repo. Today, each member’s Required Fund Deposit functions as initial margin, while all members’ deposits together form the Clearing Fund and can support mutualized losses.
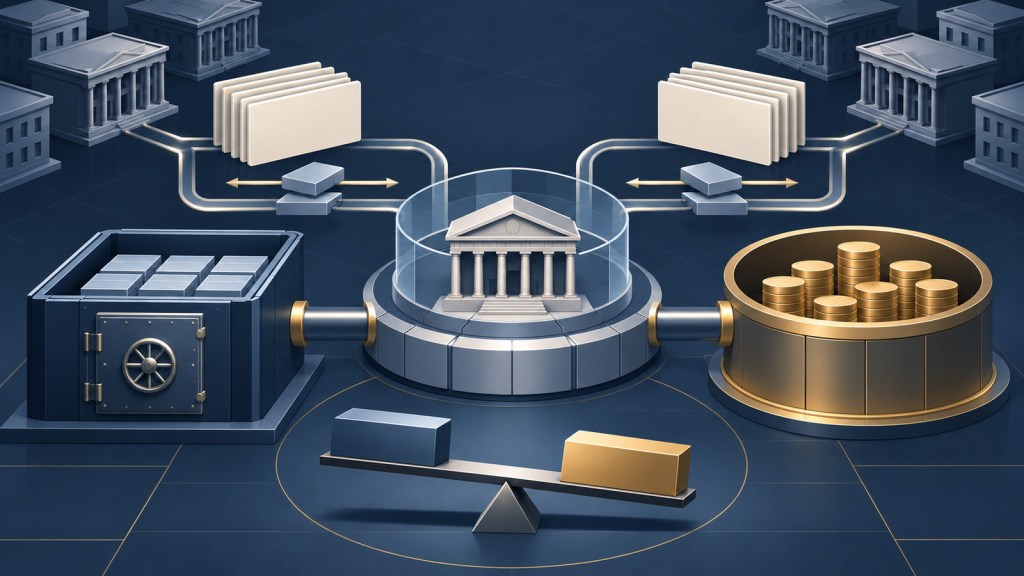
The proposal would separate those functions. Initial margin would be excluded from loss mutualization and structured to support bankruptcy-remote treatment. A new cash-only Guaranty Fund would cover residual stress losses after a defaulting member’s initial margin is applied.
FICC would size the fund to a “Cover 2” standard: the stress deficiency associated with the simultaneous default of the two member families creating the largest aggregate exposure under extreme but plausible conditions. The fund would be resized monthly, with intramonth resizing available when specified thresholds are breached. FICC’s 2025 impact study produced an average estimated fund size of approximately $6 billion, ranging from about $5.25 billion to $6.37 billion.
The proposal would also cap a member’s loss allocation during a five-business-day event period at 200% of that member’s guaranty-fund requirement. That improves the visibility of a member’s maximum assessment compared with an open-ended sequence of loss-allocation rounds, although it does not eliminate the need to fund the initial contribution.
Capital relief and cash strain are different answers
The strongest argument for the redesign is not that it makes risk disappear. It changes where risk sits and how the resources are treated.
SIFMA and the Alternative Investment Management Association supported the separate fund. Their letters argue that bankruptcy-remote initial margin could reduce regulatory-capital requirements for qualifying clearing members and release balance-sheet capacity for Treasury trading and financing. FICC also says the guaranty fund would cover stress losses that remain after initial margin, rather than duplicate the 99% margin framework.
The Independent Dealer and Trader Association reaches a different conclusion for its members. It argues that bank-affiliated firms may obtain Basel capital relief while independent broker-dealers do not receive the same benefit under SEC net-capital rules. Those firms would still have to provide cash to the new fund, potentially reducing their capacity to intermediate Treasury and repo transactions.
Both propositions can be true. A structure can improve the legal protection of initial margin and reduce capital charges for some members while increasing cash demands for others. Calling the change “capital efficient” without identifying whose capital, whose cash and which rulebook collapses three distinct questions into one favorable label.
The $6 billion number needs context
FICC’s impact study is useful, but it is historical. It covered January through December 2025, before the final shape and volume of mandatory Treasury clearing are known. IDTA also notes that the study observed no intramonth collections or resizing during that period.
That does not make the estimate irrelevant. It means finance teams should not use the average as a committed funding number. A better planning bridge would show at least:
- the member’s expected base contribution and the assumptions driving it;
- a higher-contribution case tied to larger stress deficiencies or market volatility;
- the cash deadline and available same-day sources if FICC resizes intramonth;
- the regulatory-capital benefit, if any, from bankruptcy-remote initial margin;
- the member’s maximum 200% assessment during an event period; and
- the effect on client pricing, repo capacity and Treasury-market intermediation.
The timing discipline is similar to the distinction in Bank-Resolution Funding Plans Remain Incomplete: nominal resources are not the same as cash that can move when required. It also connects to Treasury’s $1 Trillion Short-Term Borrowing Shift, because changes in Treasury-market infrastructure can alter the capacity and price of the balance sheets supporting that borrowing.
Competition is part of the risk analysis
The SEC’s order identifies competition as one of the issues under review. That is appropriate. A default fund designed to improve resilience can still create a concentration problem if its fixed and contingent funding costs push smaller intermediaries out of the market.
The opposite risk also matters. Underfunding the central counterparty or relying only on member-specific margin could leave FICC without enough prefunded resources in an extreme multi-member event. FICC argues that initial margin and a mutualized default fund serve different regulatory purposes: one covers potential future exposure during closeout, while the other covers residual stress losses beyond the defaulter’s margin.
The right comparison is therefore not “fund or no fund.” It is the full economic cost of the proposed structure against credible alternatives, including how each option affects default protection, liquidity calls, regulatory capital, market access and concentration. The SEC proceeding gives commenters another opportunity to supply that evidence.
A practical liquidity drill
Before implementation, a clearing member should run a same-day funding exercise. Assume the guaranty fund is resized after positions or volatility change. Identify the cash amount, notification time, funding deadline, authorized signers, available cash and credit, collateral consequences, and any competing settlement obligations.
The free 13-Week Cash Flow Forecast is not a substitute for a broker-dealer liquidity model, but its core discipline is relevant: separate the base case from a timing stress, identify the first breach and assign action before the cash requirement arrives.
The decision should be measured after implementation
If the proposal is approved, success should not be judged only by whether the fund reaches its required size. The better scorecard would also track the distribution of contributions, realized capital relief, changes in clearing-member participation, client pricing, repo capacity, intramonth calls and any increase in concentration.
A safer Treasury market is the objective. The guaranty fund is one design choice, and its value will depend on whether it adds resilient resources without moving too much intermediation capacity toward the firms already best positioned to absorb the cost.
Sources
- SEC Release No. 34-106834, order instituting proceedings on SR-FICC-2026-008, November 5, 2026.
- FICC proposed rule change and impact study, 91 FR 51762, August 11, 2026.
- FICC response to comments, October 13, 2026.
- Independent Dealer and Trader Association comment letter, September 1, 2026.
- SIFMA and SIFMA AMG comment letter, September 2, 2026.
- Alternative Investment Management Association comment letter, October 23, 2026.
By Robert Young | Numbers & Judgment. Published November 6, 2026.


Leave a Reply