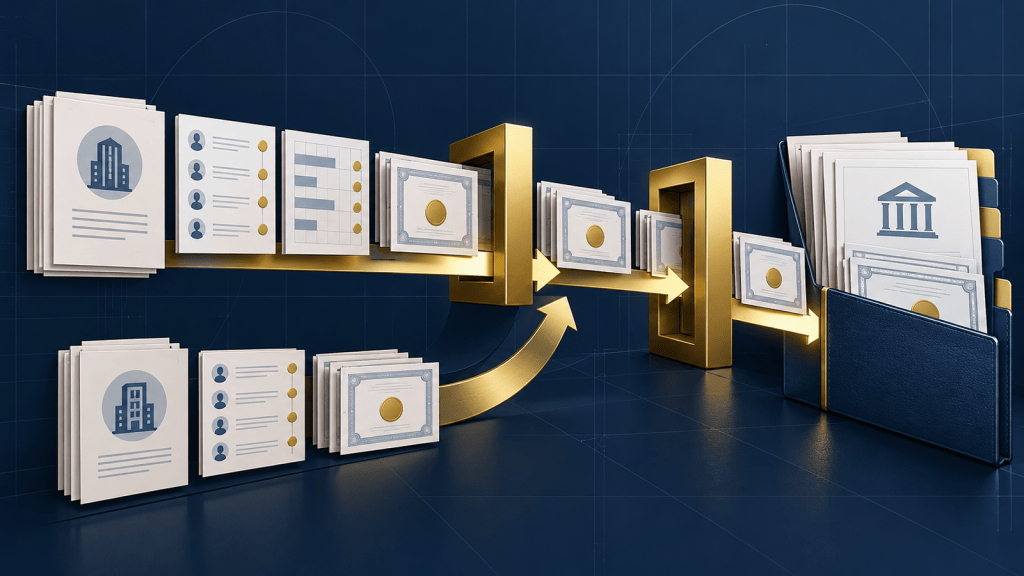
The SEC’s Division of Corporation Finance clarified on October 15 how two common equity-compensation transitions can be handled: moving outstanding private-company awards onto Form S-8 after an issuer becomes an Exchange Act reporting company, and preserving Rule 701 treatment for certain assumed awards after an acquisition.
The guidance removes a filing question. It does not remove the finance work. For a company approaching an IPO or closing an acquisition, the real test is whether the award ledger, eligibility history, approvals, valuation evidence and share counts can survive a change in legal regime without creating avoidable reporting or employee problems.
The judgment
- Implication: The SEC staff has made the Rule 701-to-Form S-8 handoff more workable, but execution risk now sits more visibly in the issuer’s award data, approvals and reconciliation controls.
- What would change the conclusion: The conclusion would weaken if later Commission action, court decisions or issuer-specific facts narrow the staff positions. The interpretations are informal staff guidance, not binding rules.
- Management action: Build a grant-by-grant transition file before the transaction deadline: recipient eligibility, award type, grant and vesting terms, governing plan, exemption or registration path, shares reserved, approvals, exercises, cancellations and required disclosures.
What the SEC staff clarified
New Securities Act Rules interpretation 271.28 addresses awards granted before a company became an Exchange Act reporting company under an exemption from Securities Act registration. Once the issuer is eligible to file Form S-8, the staff said it would not object if the issuer moves the offering onto Form S-8 by registering shares to be issued when restricted stock vests and shares underlying outstanding stock options and restricted stock units previously granted to eligible recipients.
New interpretation 271.29 addresses an acquisition. The staff said an eligible acquiring company may rely on Rule 701 for restricted stock and securities underlying options and RSUs that it assumes in the transaction, including awards held by people whose employment or service relationship with the acquired company ended before the acquisition.
Those are useful answers because equity plans often span the exact moments when a company’s legal and reporting status changes. Awards granted while private do not disappear at an IPO. Awards inherited in an acquisition do not arrive with perfectly standardized records. The SEC update gives issuers a clearer path, but it depends on knowing which awards are in the population and why each one qualifies.
The handoff is a data-reconciliation problem
Finance teams can be tempted to treat Form S-8 as a counsel-led filing. The filing is legal work; the evidence beneath it is cross-functional operating data. Stock administration, finance, payroll, tax, human resources, legal and the transfer agent may each hold part of the record.
A defensible transition starts by reconciling at least four views of the same population:
- The plan view: authorized shares, plan limits, award types and governing documents.
- The participant view: recipient status, service history, vesting conditions, exercises, cancellations and post-termination rights.
- The accounting view: grant-date records, expense recognition, modifications, forfeitures and the equity or liability classification supporting the financial statements.
- The securities-law view: the exemption or registration path supporting each grant and the disclosures delivered when required.
If those views do not agree, the company has more than a cap-table cleanup issue. It may have to resolve registration coverage, payroll and tax handling, share-reserve calculations, financial-statement evidence or employee communications under transaction pressure.
IPO readiness needs an award-conversion workstream
The new staff position makes the transition path clearer, so the management question becomes timing. A pre-IPO company should not wait until Form S-8 drafting to discover that former employees are mixed with current recipients, awards were modified without consistent records, or the equity platform does not reconcile to board approvals and the general ledger.
A practical readiness workstream can use three gates:
- Population gate: every outstanding award is tied to a recipient, plan, approval and source document.
- Eligibility gate: management and counsel have classified which awards and recipients fit the intended Form S-8 transition, with exceptions isolated rather than buried in the main file.
- Reconciliation gate: shares reserved, granted, vested, exercised, forfeited, cancelled and available agree across the equity system, board records, transfer-agent data and financial reporting.
This extends the broader point in DeepSeek’s First CFO Signals AI’s Next Phase: public-market readiness is an operating-system change, not only a financing event. It also complements the analysis in SEC $2B Threshold: What Internal-Control Assurance Is Worth. A regulatory threshold can change, but management still owns the quality of the underlying control evidence.
Acquisitions need the same discipline before close
Interpretation 271.29 is especially relevant when an acquirer assumes awards from a target with former employees or service providers in the population. The staff’s answer reduces one uncertainty, but it does not validate the target’s records.
Equity diligence should therefore connect the legal schedule to the purchase-accounting and integration files. Management should identify award modifications, acceleration provisions, change-in-control terms, former-worker rights, withholding obligations and any gap between the target’s equity platform and approved agreements. The objective is not merely to calculate deal consideration. It is to prevent an inherited award population from becoming a post-close control exception.
What the audit committee should see
The audit committee does not need a line-by-line award register. It should receive a compact exception report showing:
- total awards and underlying shares by intended registration or exemption path;
- unreconciled differences among the equity platform, approvals, transfer-agent records and the general ledger;
- awards with missing agreements, disputed terms or unresolved eligibility;
- former employees and service providers whose awards require separate review;
- owners and due dates for each exception; and
- the final sign-off required before filing or closing.
The free Board Finance Dashboard can serve as a simple shell for the exception, owner, deadline and decision log, although a transaction should use a dedicated equity subledger for award-level detail.
The SEC staff has clarified a route through two transaction boundaries. The finance lesson is narrower and more durable: a workable legal path only creates value when the company can prove which awards are traveling on it.
Sources
- SEC Division of Corporation Finance, “Corporation Finance Interpretations Update: October 15, 2026”.
- SEC Securities Act Rules Corporation Finance Interpretations, Questions 271.28 and 271.29, updated October 15, 2026.
- SEC Corporation Finance Interpretations landing page, explaining the nonbinding status of staff interpretations.
The SEC update and quoted staff positions are reported facts. The control, readiness and governance recommendations are Numbers & Judgment analysis and are not legal advice.


Leave a Reply