“Maintain three months of operating expenses in reserve.”
That sounds like a reserve policy.
It is really a reserve target.
A useful reserve policy has to answer a harder set of questions: When can the money be used? Who can authorize a draw? How far below the target can the organization go? What happens afterward?
The National Council of Nonprofits recommends that reserve policies address the amount to be set aside, the circumstances that permit use, the decision process, repayment timing, and any restrictions or limitations.
That is the difference between having reserves and governing reserves.
Start with a target, not a universal rule
There is no single reserve level that is right for every organization.
A business with recurring monthly revenue, few fixed assets, and flexible costs can tolerate a different reserve level from an organization with seasonal fundraising, aging facilities, concentrated revenue, or large contractual commitments.
The target should reflect risk.
- How volatile is revenue?
- How concentrated is funding?
- How quickly can expenses be reduced?
- How much deferred maintenance exists?
- How seasonal is cash flow?
- What unexpected obligations could appear?
The reserve target is the starting point. Trigger points make it operational.
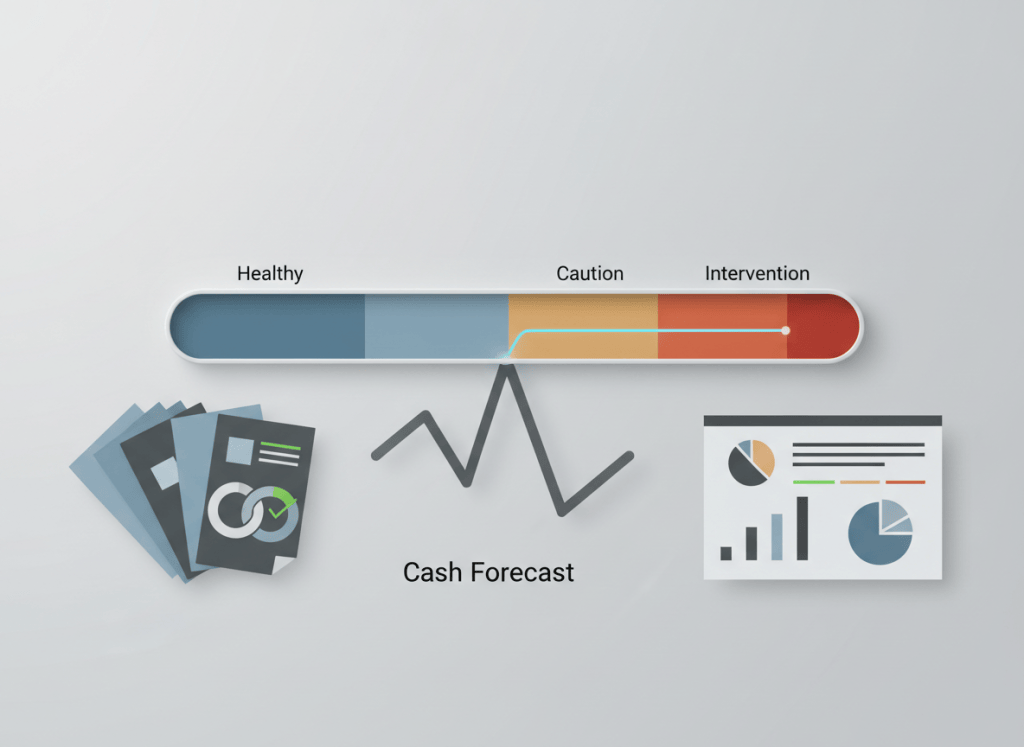
Build a green, yellow, and red framework
One simple approach is to define reserve zones in advance.
Green: normal operating range
The reserve is at or above target. Management can operate normally, subject to the approved budget and investment policy.
Yellow: heightened attention
The reserve has fallen below the target or is forecasted to do so. Management develops a recovery plan, increases cash forecasting, and reports more frequently to the board or finance committee.
Red: formal intervention
The reserve has fallen below a minimum threshold. Discretionary spending, hiring, capital commitments, or other decisions may require additional approval until the financial position improves.
The exact thresholds will differ by organization. The important point is to decide them before the crisis.
Define the events that justify a draw
A reserve should not become a convenient plug for every unfavorable budget variance.
Potential trigger events might include:
- a temporary and material revenue shortfall
- unexpected facility or equipment failure
- a timing gap between spending and grant reimbursement
- emergency response costs
- a deliberate restructuring that requires one-time transition expense
- a strategic investment specifically authorized by the board
Each organization should decide which uses are appropriate and which are not.
Reserves should absorb shocks or enable deliberate choices—not hide a recurring business-model problem.
Separate temporary deficits from structural deficits
This is one of the most important tests.
Using $500,000 of reserves because a committed grant arrives three months late is fundamentally different from using $500,000 every year because recurring revenue does not cover recurring expenses.
The first is liquidity support.
The second may be a structural deficit.
A good policy should force management and the board to name the difference.
Create an authority matrix
Who can authorize use of reserves?
The answer might depend on the size and purpose of the draw.
- Management may have authority for small, temporary cash-timing needs.
- The finance committee may approve larger draws within defined limits.
- The full board may be required for material draws, strategic uses, or any action that pushes reserves below a minimum threshold.
Whatever structure is chosen, the policy should eliminate ambiguity during a stressful moment.
A draw needs a replenishment plan
The decision to use reserves should include a second decision: how will they be rebuilt?
A replenishment plan can specify:
- the target restoration date
- the portion of future surpluses directed to reserves
- restrictions on new discretionary commitments until the target is restored
- fundraising or financing actions, if appropriate
- the reporting cadence to the board
That does not mean every reserve draw must be repaid immediately. It means the organization should understand the path back to resilience.
The board should see the reserve forecast, not just the balance
Every board package should show the current reserve balance, approved or expected draws, expected replenishment, and the forecasted year-end balance.
That changes the conversation from:
“We have $4 million in reserves.”
to:
“We have $4 million today, expect to use $1.2 million this year, and have a plan to restore $600,000 next year.”
The second statement is much more useful.
A reserve policy is really a decision policy
The balance matters. But the governance around the balance matters just as much.
A good reserve policy tells an organization what to do before financial stress turns into improvisation.
Without trigger points, authority, and a replenishment plan, a reserve target is just a number on a page.
Source: National Council of Nonprofits — Operating Reserves for Nonprofits.


Responses
[…] is where a reserve policy becomes an operating decision tool. A reserve policy needs trigger points, approval authority and a replenishment or exit plan. During a wind-down, the same logic should […]
LikeLike
[…] policy: authority, triggers and replenishment rules matter more than the headline balance. See A Reserve Policy Without Trigger Points Is Just a Number. The HomeRise case also illustrates how delayed control remediation can turn into a […]
LikeLike
[…] while the organization adds program-specific milestones and restrictions. The related lesson from reserve policies with trigger points also matters: temporary support for a documented reimbursement gap is different from using […]
LikeLike
[…] board-level action thresholds, see A Reserve Policy Without Trigger Points Is Just a Number. For the way financing stress can become a mission-continuity problem, see HomeRise Wind-Down Puts […]
LikeLike
[…] Household Wealth Rose While Payment Stress Worsened examines divergent economic indicators; A Reserve Policy Without Trigger Points Is Just a Number covers reserve decision rules. The free 13-Week Cash Flow Forecast can help translate changing […]
LikeLike
[…] are most useful when policy defines the conditions for using them and the path for rebuilding them. A Reserve Policy Needs Trigger Points explains why a target should be paired with authority, intervention levels and a replenishment […]
LikeLike
[…] related principle appears in A Reserve Policy Without Trigger Points Is Just a Number. A reserve is most useful when policy defines the purpose, authorization and replenishment path. It […]
LikeLike