A federal grant can clear one risk and leave another. The immediate threat that nearly $289 million of fiscal-year 2025 Community Development Financial Institutions funding could expire has receded: the Treasury Department told a federal court that the money was obligated on September 23.
That is a meaningful change from September 21, when plaintiffs alleged that Treasury had announced awards but had not completed the recipient-level obligations. It is not the same as cash arriving in every recipient’s bank account.
Update, September 26, 2026: This article has been revised to reflect Treasury’s sworn declaration and the government’s subsequent statement in court that the fiscal-year 2025 CDFI Program funds were obligated on September 23.
The judgment
- Implication: The September 30 expiration risk is now substantially lower, but obligation resolves only one step in the grant-to-cash chain. Recipient notification, agreement execution, compliance, draw access and cash timing still matter.
- What would change the conclusion: Recipient-level notices, completed assistance agreements and evidence of payment access would justify moving the funding from “obligated” toward a firmer cash assumption. Until then, the precise receipt dates remain uncertain.
- Management action: Update the cash forecast to reflect the reduced expiration risk, but do not replace a range of possible receipt dates with a single guaranteed date. Track each award from notice through usable cash.
What changed
On September 15, Treasury’s CDFI Fund announced fiscal-year 2025 CDFI and Native American CDFI Assistance awards, along with awards under two other programs. The official notice said the underlying appropriations would otherwise expire on September 30, 2026, and that organizations would receive notices through Treasury’s award-management system by that date.
A coalition representing CDFIs then sued Treasury and the Office of Management and Budget. Reuters reported on September 21 that the plaintiffs alleged Treasury had not identified recipients or obligated the nearly $300 million at issue, creating a risk that the authority would expire before it could be used.
The factual position changed two days later. In a sworn declaration dated September 22, CDFI Fund Director Christopher Miller said budget authority becomes obligated when the Fund emails a Notice of Award to a successful applicant. He said the Fund expected approximately $288,992,757—nearly the full $289 million—to be obligated by close of business September 23.
On September 25, Democracy Forward, counsel for the plaintiffs, said the government’s lawyer told the court that the funds had in fact been obligated on September 23. That account is from a party to the litigation, not a final judicial finding. The plaintiffs also said they were seeking a further sworn statement and that the court scheduled another hearing for September 29.
The cautious conclusion is therefore narrow: the best available evidence indicates that the fiscal-year 2025 CDFI Program money was obligated before expiration. Questions about distribution, recipient access and the broader litigation remain.
Obligation is a legal milestone, not a bank balance
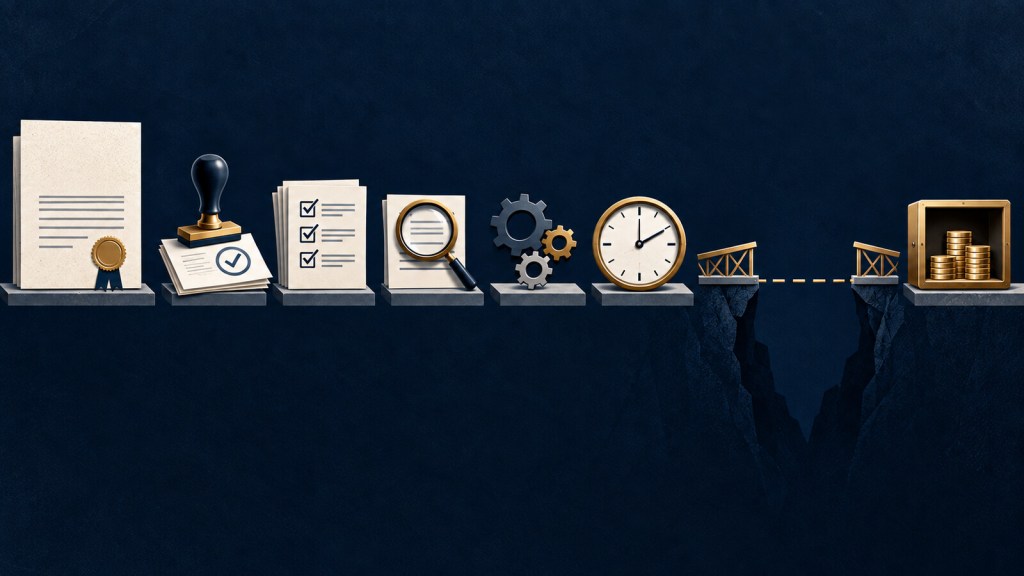
Finance teams often compress a long funding process into one status: “the grant is awarded.” The CDFI dispute shows why that shorthand is risky. A more useful grant-to-cash ladder separates at least eight stages:
- Appropriation: lawmakers provide budget authority for a purpose.
- Program availability: the agency publishes rules, terms and an application process.
- Selection or announcement: the agency identifies awards or selected applicants.
- Obligation and notice: the government legally commits the funds and issues recipient-level notice.
- Agreement and compliance: the recipient accepts terms and satisfies documentation or system requirements.
- Draw or reimbursement eligibility: the recipient can request payment, sometimes only after incurring costs.
- Cash receipt: the money reaches the organization’s account.
- Usable cash: the funds can legally and operationally support the obligation management is trying to fund.
Treasury’s declaration moves the relevant funds from stage three to stage four. That is consequential because it addresses the risk that unobligated authority would lapse. It does not collapse stages five through eight into the same date.
The risk has shifted
Before September 23, the central risk was binary: would the government obligate the funds before the fiscal deadline? After obligation, the risk becomes operational and temporal. Recipients need to know when notices arrive, what conditions apply, when agreements become effective and when cash can be drawn.
Those distinctions matter because CDFIs use capital for lending, loan-loss reserves, capacity building and financial services in communities with limited conventional credit access. A legally preserved award can still leave a recipient financing payroll, vendors or lending commitments during the gap between notice and payment.
That bridge has a price. Interest expense is the obvious cost. Less visible costs include reserve depletion, delayed lending, management distraction and the possibility that temporary cuts weaken future operating capacity.
What boards should ask now
The board question should no longer be only, “Will the appropriation expire?” It should become, “Where is each award on the path to usable cash, and what must the organization finance before it arrives?”
- Has the organization received its Notice of Award?
- Has management reviewed and accepted the assistance agreement?
- What compliance, matching or documentation conditions remain?
- Is payment advanced, drawn or reimbursed after spending?
- What is the earliest plausible cash date, and what could delay it?
- Which commitments depend on the award, and what is the contingency plan?
This is the same distinction described in A Balanced Budget Can Still Hide a Cash Crisis: revenue recognition, budget inclusion and liquidity answer different questions. It also connects to the analysis of private-capital mobilization, because catalytic public funding should be evaluated by both its face amount and the additional lending capacity it enables.
Keep the forecast probabilistic
The new evidence should improve the forecast without creating false precision. Management can increase confidence that the funds will survive the fiscal deadline while preserving a range for recipient-level cash timing.
A rolling 13-week cash flow forecast is useful here. Show the award in the week cash is realistically expected to clear, not the week it was announced or obligated. Maintain a later case that includes the real response sequence: when a credit line is drawn, what spending pauses, which commitments remain protected and when the board is notified.
The central lesson survives the good news. An appropriation, an award announcement, a legal obligation and spendable cash are different assets. Finance leaders should name each stage precisely—and update decisions when the evidence changes.
Sources
- U.S. Treasury CDFI Fund, FY2025 and FY2026 awards announcement, September 15, 2026.
- Declaration of CDFI Fund Director Christopher Miller, filed September 22, 2026.
- Reuters, “Trump administration sued over withheld federal grants for US community lenders,” September 21, 2026.
- Democracy Forward, counsel for the plaintiffs, September 25, 2026.
Reported facts, sworn statements and litigants’ claims are identified separately above. The grant-to-cash framework and management recommendations are Numbers & Judgment analysis.


Responses
[…] is why the distinction in the CDFI grant-to-cash analysis matters, and why a balanced budget can still hide a cash crisis. The same discipline applies to […]
LikeLike
[…] is the same discipline discussed in Treasury Obligated $289 Million. CDFIs Still Need a Cash Plan: appropriation, obligation, award execution and spendable cash are different assets. The […]
LikeLike
[…] is the same discipline behind our analysis of why an award, obligation and usable cash are different assets. A multiyear commitment can support strategy while still creating a near-term working-capital […]
LikeLike
[…] Services at Risk examines the limit of restructuring when essential capacity has already been cut; Treasury Obligated $289 Million. CDFIs Still Need a Cash Plan separates committed funding from usable liquidity. The free Nonprofit Program & Grant […]
LikeLike