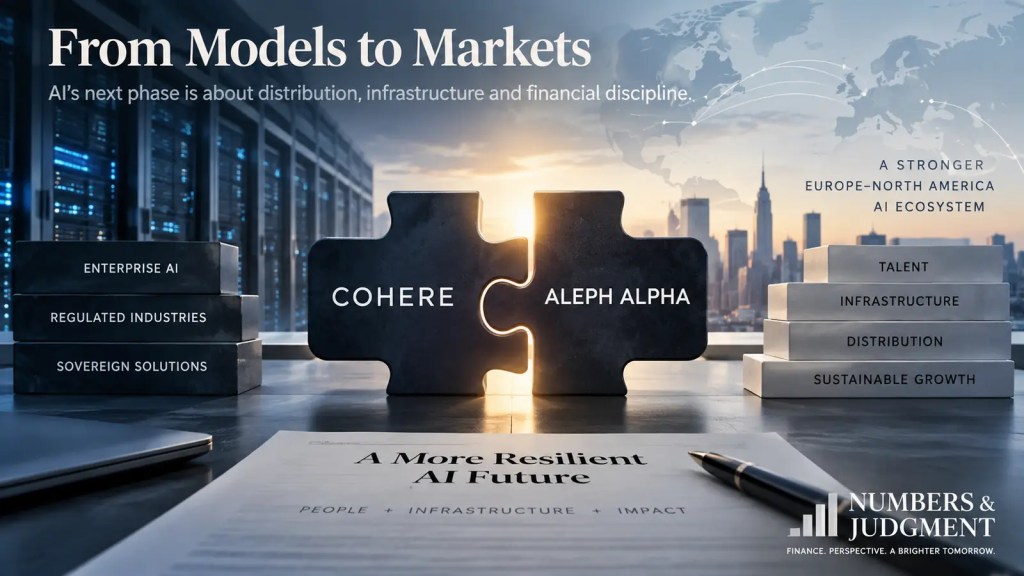
The Cohere–Aleph Alpha Deal Shows AI Is Entering a Capital-Efficiency Phase
By Robert Young · September 16, 2026 · 7:45 AM PT
For most of the generative-AI boom, the strategic question has been straightforward: who can build the best model?
The combination of Canada’s Cohere and Germany’s Aleph Alpha suggests the next phase may be governed by a different question:
Who can turn enormously expensive AI capabilities into durable enterprise cash flow?
Cohere and Aleph Alpha announced Wednesday that they have signed a definitive business-combination agreement, formalizing a plan first disclosed in April. The combined company will operate as Cohere, with dual headquarters in Toronto and Berlin and more than 1,000 employees across Canada and Europe. The transaction remains subject to regulatory approval. Cohere and Aleph Alpha announcement, September 16, 2026
Reuters reports that the combination was valued at roughly $20 billion when initially disclosed. Schwarz Group, the owner of Lidl, is investing €500 million in the combined business and will provide computing capacity through its STACKIT cloud operation. Cohere reported roughly $240 million in annual recurring revenue, while Aleph Alpha’s latest publicly reported revenue was less than €1 million in 2023. Reuters, September 16, 2026
Those numbers make the transaction more interesting than the headline valuation.
AI has a fixed-cost problem
Building competitive AI systems requires unusually large fixed investments: researchers, engineers, chips, data centers, energy, model training, security, compliance and increasingly sophisticated enterprise integration.
That creates familiar economics. When fixed costs become enormous, scale matters more. Two organizations independently funding overlapping research, infrastructure and go-to-market capabilities may eventually create less value than a combined organization spreading those costs across a larger revenue base.
This is why the Cohere–Aleph Alpha transaction should be viewed partly as a capital-allocation decision rather than simply an AI-industry merger.
Aleph Alpha’s pivot may be the most revealing part
Aleph Alpha was once positioned as a European contender in frontier-model development. It has increasingly shifted toward specialized models and integration for governments and regulated industries.
That does not necessarily represent technological retreat. It may represent financial discipline.
There is little economic value in winning a technical benchmark if the cost of remaining competitive continually outruns the revenue available from customers. The rational strategic response can be to move up the value chain: integrate models into customer workflows, solve regulatory and data-sovereignty problems, and monetize institutional relationships that are difficult for competitors to reproduce.
Cohere brings broader model-development and enterprise deployment capabilities. Aleph Alpha brings research expertise and established relationships in European government and regulated markets. Schwarz Group brings capital and infrastructure.
Viewed through a CFO lens, those are complementary assets rather than simply complementary technologies.
The real moat may be deployment, not the model
Generative AI models are improving quickly, but the underlying technology is also becoming more widely available. That creates a strategic risk for companies whose value proposition rests primarily on model performance.
Enterprise customers—particularly banks, insurers, governments, healthcare organizations and other regulated institutions—often care about a different set of questions:
- Where does our data reside?
- Who can access it?
- Can the system run inside our own infrastructure?
- Can we audit how it operates?
- Does it comply with local regulation?
- Can it integrate with the systems where our employees actually work?
Those capabilities are less glamorous than another model benchmark. They may also be easier to monetize.
The companies explicitly describe the combination as a sovereign-AI strategy: offering organizations more control over their technology, infrastructure and sensitive data. Cohere also announced a separate partnership Wednesday with OpenText aimed at bringing agentic AI to governments and regulated industries, reinforcing the same enterprise-distribution strategy. OpenText and Cohere announcement, September 16, 2026
Infrastructure is becoming part of the transaction
The Schwarz Group relationship is particularly important. The group committed €500 million in structured financing when the transaction was initially announced and is building substantial European data-center capacity through STACKIT. Reuters reports that Schwarz is investing €11 billion to €13 billion in a German data-center campus expected to accommodate as many as 100,000 AI chips.
That illustrates how AI competition is expanding beyond software. Capital, computing capacity, energy, distribution and regulatory positioning increasingly sit alongside model quality as strategic assets.
For finance leaders, this matters because the economics of those assets are different. Software can scale at extraordinary incremental margins. Data centers and computing commitments require enormous capital before revenue arrives.
The more infrastructure becomes part of the AI stack, the more important utilization, return on invested capital and financing structure become.
The CFO lesson: sometimes consolidation is the growth strategy
Companies often describe acquisitions as a way to accelerate growth. The more interesting rationale is sometimes avoiding duplicated investment.
If two businesses each need to fund research, infrastructure, compliance, enterprise sales and implementation capabilities, combining those businesses can change the denominator of the entire economic model.
The relevant question is not simply whether the combined company generates more revenue. It is whether it can generate that revenue with less incremental capital per dollar of growth.
That is the metric worth watching as the transaction closes and the companies integrate.
The next AI winners may look different
The first phase of generative AI rewarded technical breakthroughs and access to enormous amounts of capital. The next phase may reward something more mundane: operating leverage.
Companies will still need strong models. But model quality alone may not justify the cost of independently maintaining frontier capabilities, particularly when customers increasingly care about security, integration, sovereignty and measurable return on investment.
That means the AI market could begin to resemble other capital-intensive industries. Scale becomes valuable. Infrastructure partnerships matter. Distribution becomes a moat. Smaller competitors specialize. And consolidation becomes an economically rational response to rising fixed costs.
The next phase of AI may not be won by the company that spends the most to build the smartest model. It may be won by the company that converts AI’s enormous fixed costs into the most durable cash flow.
Related reading: The CFO as AI capital allocator; AI financing and balance-sheet risk; and AI governance in finance.
Sources
- Cohere and Aleph Alpha — definitive business combination announcement, September 16, 2026
- Reuters — Cohere, Aleph Alpha combine to target enterprise AI market, September 16, 2026
- Cohere — original combination announcement and Schwarz Group financing
- OpenText and Cohere — enterprise agentic AI partnership, September 16, 2026
 Numbers & Judgment

Responses
[…] reading: AI governance in finance; AI financing and balance-sheet risk; and AI’s capital-efficiency phase. Source: Deloitte, Finance Trends […]
LikeLike
[…] Related reading: The CFO as AI capital allocator; what a 5% Treasury yield changes; and AI’s capital-efficiency phase. […]
LikeLike